Selling House With HELOC in Maryland: What Nigerian Sellers Should Do
Selling a house with a HELOC debt in Maryland is usually possible without paying the line off before you list. The HELOC is tied to the property, so the balance normally must be paid and the lien released when the sale closes. Your real decision is whether the expected sale proceeds can cover your first mortgage, HELOC, selling costs, and the cash you need next.
For Nigerian and African homeowners in Bowie, Upper Marlboro, Hyattsville, Clinton, Lanham, and nearby Prince George’s County communities, I start with numbers. A HELOC can reduce what you keep, but it does not automatically block a sale.
Can You Sell a House With a HELOC Still Open?
Yes. Can you sell a house with a HELOC? In most normal sales, you can.
A HELOC is a revolving credit line secured by your home. Because the property secures that debt, the lender has a lien interest that must be addressed before clear title transfers. The Consumer Financial Protection Bureau’s HELOC guidance explains how this open-end credit is secured by home equity.
You usually do not need to pay the HELOC from savings just to put the home on the market.
Before listing, confirm four numbers:
- Expected Maryland sale price.
- First mortgage payoff.
- HELOC payoff.
- Estimated selling and closing costs.
Those figures tell you whether the sale has enough equity to work.
What Happens if You Sell a House With a HELOC?
The payoff normally happens through settlement.
The settlement or title company obtains payoff information, pays secured debts from the sale proceeds, and distributes what remains after other closing charges.
In a common lien order, the first mortgage is paid before a later HELOC. Exact priority depends on the recorded liens and transaction history.
Maryland land records include mortgages, deeds of trust, liens, and releases. The state’s Maryland Land Records guidance also explains why lien review matters when property transfers.
Use the Payoff Amount, Not Your Online HELOC Balance
Your current account balance is not always the amount needed to close the line.
A payoff amount can include:
- Outstanding principal.
- Interest through the payoff date.
- Unpaid fees.
- Possible early-closure charges.
- Other amounts required by your agreement.
Federal rules generally require an accurate payoff statement within seven business days after a written request for qualifying consumer credit secured by a dwelling.
Request it early enough to solve errors before settlement.
If the HELOC is still in its draw period, avoid new draws while the sale moves toward closing. A new advance can change the payoff amount.
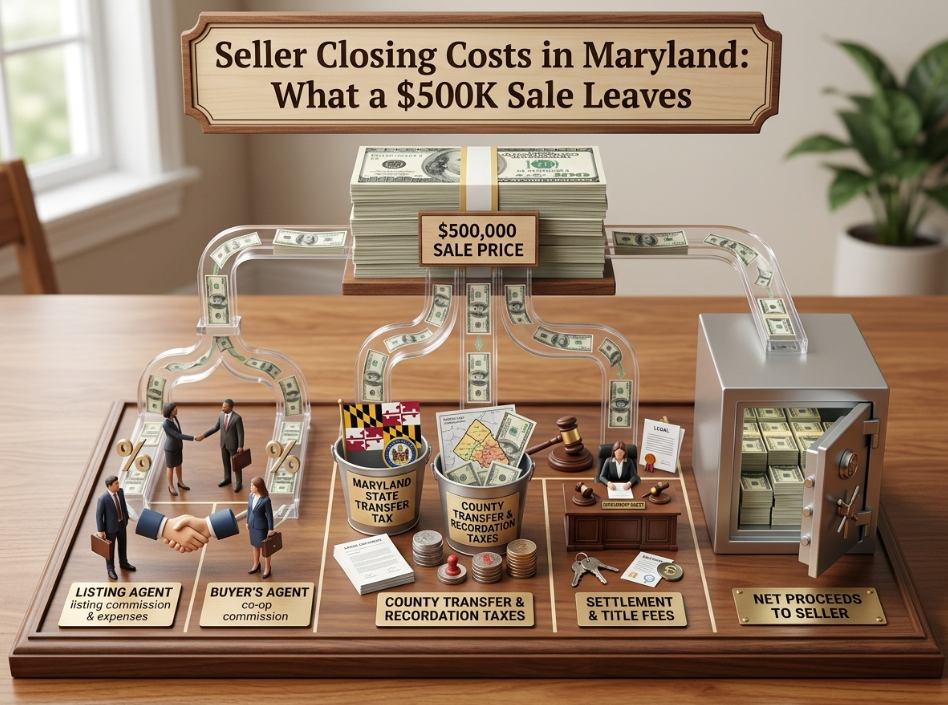
Calculate What You Could Actually Keep From the Sale
A Nigerian seller may see strong equity online but still overestimate the cash available after closing.
Use this planning formula:
Expected sale price
minus first mortgage payoff
minus HELOC payoff
minus seller costs and negotiated credits
equals estimated cash before taxes and moving costs
| Item | Example |
| Maryland sale price | $485,000 |
| First mortgage payoff | $280,000 |
| HELOC payoff | $45,000 |
| Assumed seller costs and credits | $30,000 |
| Estimated amount remaining | $130,000 |
This is an illustration, not a property quote. Actual costs depend on the contract, loan documents, taxes, and settlement.
That $130,000 figure is more useful than saying the home has $205,000 of gross equity.
If a buyer also requests closing help, review how seller concessions affect your Maryland net proceeds before judging the offer by price alone.
Pay Off the HELOC First or Let Closing Pay It?
For many sellers, paying the HELOC from sale proceeds is the simpler path.
Paying it earlier may make sense when you already have the cash or need to solve a title or financing issue before marketing.
Waiting until closing may make more sense when:
- The home has enough equity.
- You do not want to use savings.
- The payoff can be handled normally at settlement.
- You need cash for your next move.
- Early payoff offers no meaningful benefit.
Do not drain an emergency fund simply to make the listing look debt-free.
The key question is whether the home can deliver the net proceeds you need after both loans are cleared.
What if the HELOC Balance Is Zero but the Line Is Open?
A zero balance and a closed HELOC are not always the same thing.
Because a HELOC is open-end credit, the account can remain available for borrowing during its draw period. If the line still creates a recorded lien against the property, it may need formal closure and release before title transfers cleanly.
Tell the settlement company about the HELOC even if you believe nothing is owed.
Can You Sell a House With a HELOC Balance and Little Equity?
Yes, but this is where the numbers can become difficult.
Suppose your Bowie home may sell for $430,000, but you owe:
- $350,000 on the first mortgage.
- $55,000 on the HELOC.
- $25,000 in estimated selling costs.
Your estimated obligations already total $430,000.
There may be little left for buyer credits, taxes, moving costs, or your next down payment.
If expected proceeds cannot satisfy secured debts and closing costs, address the shortfall before accepting an offer. Options may involve bringing cash, changing the sale plan, or working with lenders when a normal payoff is not possible.
Does a HELOC Make Selling a Maryland Home Harder?
Usually, it changes the financial calculation more than the marketing.
Buyers care about receiving clear title. They generally do not need your HELOC to disappear before they tour the home or submit an offer.
Potential complications include:
- Incorrect payoff figures.
- Old lien records.
- A HELOC paid but never properly released.
- Recent draws that change the balance.
- Early termination fees.
- Not enough equity.
- Another judgment, tax lien, or HOA issue.
Maryland Courts advises people transferring property to consider professional help locating liens because not every lien appears in the same record system.
Maryland Market Value Matters Before You Decide to Wait
Your HELOC balance is only one side of the equation. Current property value determines how much room you have.
Prince George’s County had a median listing price around $459,000 in September 2026. Median days on market were about 46 days, and active listings were higher than a year earlier.
That does not mean your Bowie, Upper Marlboro, Hyattsville, Clinton, or Lanham home is worth the county median.
Condition, neighborhood, updates, lot, layout, competition, and recent comparable sales matter more.
If waiting six months means paying the mortgage, HELOC interest, insurance, taxes, utilities, and maintenance, compare those carrying costs with the realistic benefit of waiting.
Nigerian Sellers Should Plan Around the Next Use of Their Equity
For many families, the money left after selling already has another job.
You may need it to:
- Buy your next Maryland home.
- Increase a down payment.
- Move within the DMV.
- Relocate outside Maryland.
- Support a rental-property purchase.
- Keep a larger cash reserve.
That makes the HELOC payoff part of the moving strategy, not merely a closing detail.
If you expect $150,000 after both loans are paid, do not plan your next purchase around $200,000 of gross home equity.
If another purchase is part of the plan, I can also help you coordinate the transition through my Maryland home buying process.
What Should You Do Before Listing a Maryland Home With a HELOC?
I would organize the debt and property numbers before setting the asking price.
Start here:
- Estimate the home’s current market value.
- Request the first mortgage payoff.
- Request the HELOC payoff.
- Review the HELOC agreement for closure fees.
- Tell the title or settlement company about the line.
- Check for other known liens.
- Estimate seller costs and likely credits.
- Decide how much cash you need after closing.
Then build the pricing strategy around your actual goal.
My Maryland home selling process focuses on pricing, preparation, marketing, offer comparison, negotiation, and closing across Prince George’s County and the wider DMV.
Sell Based on Your Net Equity, Not Fear of the HELOC
Selling a house with HELOC debt does not usually mean you must delay your Maryland sale until the line is paid from your own pocket.
Know the payoff early and calculate what remains.
For a Nigerian or African seller, compare:
- Current local value.
- Mortgage payoff.
- HELOC payoff.
- Selling costs.
- Carrying costs if you wait.
- Expected cash after closing.
- Money needed for the next move.
If those numbers work, the HELOC may simply become another payoff handled at settlement.
At The Eze Way, I help sellers understand the real estate side of that decision, including local value, pricing, preparation, offers, and likely net proceeds.
If you are considering a sale in Prince George’s County or the wider DMV, review the Maryland property and payoff numbers with me before deciding whether waiting or listing now gives you the stronger position.